Intercompany Is Where Your Close Actually Goes to Die
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Donec rhoncus neque sed nibh sagittis, fringilla porttitor ipsum tristique. Nulla interdum ex et nisi vehicula, id laoreet nisl ultricies. Phasellus vitae magna ac lacus dictum tincidunt. Sed iaculis metus nec viverra pulvinar. Etiam id nisi eu turpis mattis imperdiet ac ac tortor. Aliquam at ipsum dui. Etiam pharetra consequat massa. Aenean nec lectus sit amet metus pharetra dapibus. Pellentesque interdum ex eget nisi fringilla, id semper erat rhoncus. Suspendisse lectus leo, malesuada pharetra commodo a, sollicitudin eu erat. Nullam justo nisl, tincidunt vel auctor id, luctus a tellus.
Aliquam convallis condimentum volutpat
Pellentesque sollicitudin mauris sit amet enim volutpat, at faucibus sem laoreet. Morbi egestas ex non orci interdum, ut elementum orci faucibus. Maecenas et sem convallis erat dignissim facilisis. Quisque purus sapien, pellentesque euismod varius id, fermentum nec nibh. Integer commodo dignissim ipsum, ac accumsan metus fringilla sit amet. Aenean aliquam sem finibus tempor venenatis. Aliquam ac facilisis turpis, eu posuere ipsum.

In nisi dui, ultricies sit amet gravida vel, ullamcorper vel mauris. Aliquam nec sapien odio. Sed vitae suscipit felis. Nullam semper blandit lectus, eu finibus urna fermentum et. Aliquam vehicula ligula nibh, non efficitur massa iaculis et. Vestibulum vitae euismod odio, non maximus nulla. Sed viverra porta enim ac interdum. Maecenas auctor tristique auctor. Nullam et neque nec tortor malesuada ullamcorper. Pellentesque ac fringilla ante, non convallis est. Proin velit augue, rutrum vitae ipsum vel, malesuada dictum urna. Nunc vulputate sit amet odio vitae ullamcorper. Nullam suscipit ornare eros, et viverra sapien hendrerit quis. Donec odio eros, ultricies a risus quis, efficitur elementum turpis. Etiam interdum diam quis turpis ultricies.
Sed euismod quam vestibulum
Sed non sapien eros. Duis fringilla fringilla lectus sit amet aliquam. Aliquam erat volutpat. Vivamus molestie, felis rutrum luctus pulvinar, libero metus eleifend mauris, semper malesuada ante eros vitae eros. Phasellus vitae dolor faucibus, laoreet lectus quis, placerat nisi. Nam ornare nulla id est aliquet, quis fringilla neque congue. Duis facilisis sed massa vel bibendum. Curabitur sollicitudin tristique commodo. Vivamus facilisis venenatis nibh. Integer placerat elementum felis, id consequat lorem consectetur a. Duis laoreet sit amet nisl in eleifend. Interdum et malesuada fames ac ante ipsum primis in faucibus.
Proin eros lacus, pellentesque sed vehicula a, luctus non nibh. Nulla diam sem, posuere ac odio varius, ultrices tristique nibh. Morbi dictum scelerisque convallis. Praesent faucibus lorem lacus, id luctus justo feugiat et. Curabitur eget tellus non nisi interdum blandit. Maecenas pulvinar est sed ex elementum, ac commodo diam bibendum. Nulla auctor dolor felis, sit amet euismod ante eleifend non. Donec id neque magna.
APQC's benchmark data says the top performers wrap the annual close in 10 days or less, the median organization takes 18, and the slowest quarter grinds through 35 - and if you ask any controller running a multi-entity group where that gap comes from, you'll hear the same word before you finish the question. Intercompany. It's the one part of the close that depends on somebody else's ledger being right, on somebody else's timing, on somebody else caring as much as you do, which is exactly why it slips.
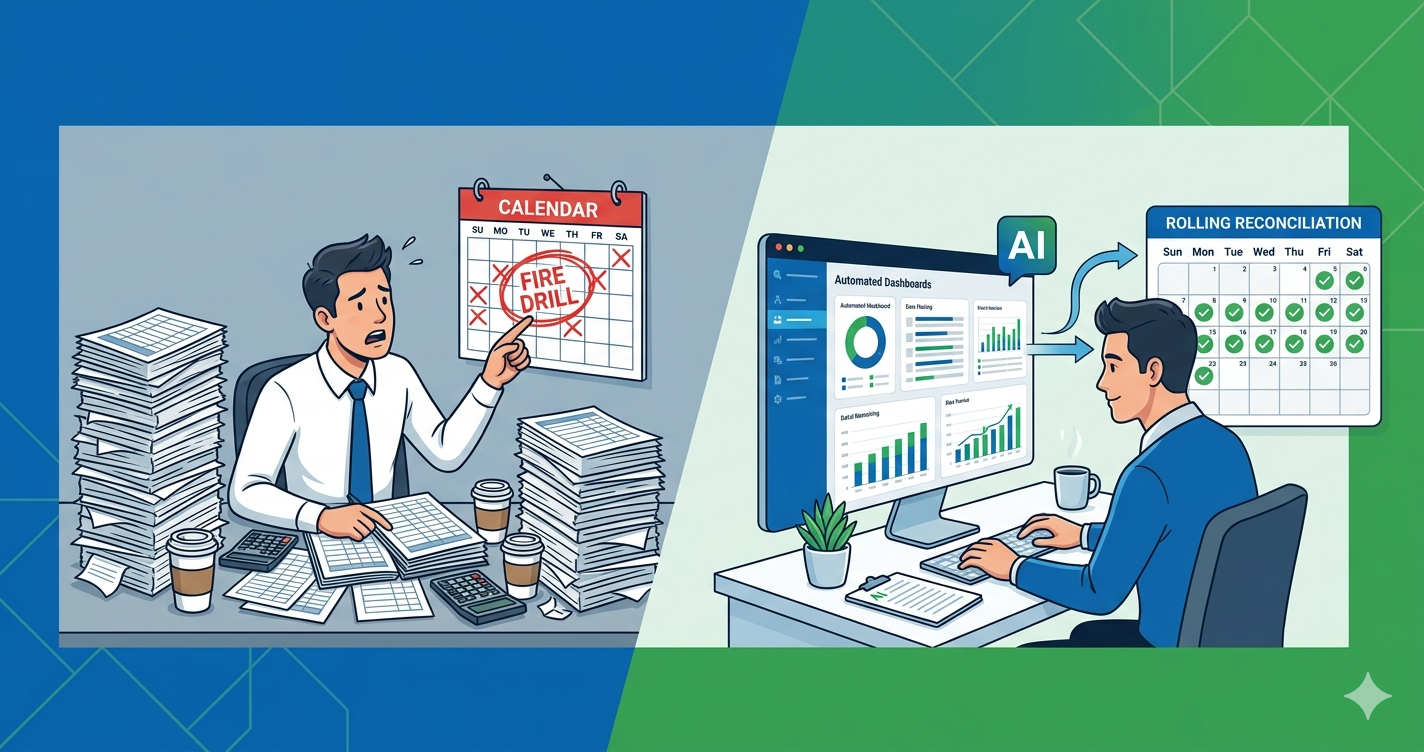
The interesting part is that intercompany is also the single most automatable thing in the entire close, because almost all of the pain is matching and chasing rather than judgment. So I want to walk through where the days actually go, what AI handles well here today, and where it still needs you - because this is the highest-leverage AI project most controllers have sitting untouched in front of them.
Where do the close days actually go?
Size matters more than most benchmarking conversations admit. APQC's research on the annual close shows organizations under $100 million in revenue running a median annual close of 10 days, while $1 billion to $5 billion companies sit at 23. That jump isn't because bigger companies have worse accountants. It's because entity count scales the reconciliation surface faster than headcount scales, and every new entity you add multiplies the pairs that have to agree with each other.
Once you're consolidating, the entity closes stop being the finish line and become the input. You still owe currency translation, intercompany eliminations, and group statements after every subsidiary says it's done, and that tail is where the calendar quietly eats you. APQC's own guidance on the subject leads with reconciling intercompany transactions EARLY, which tells you where they think the bottleneck sits too.
Why intercompany breaks in the first place
Four things, over and over. Timing - entity A books the charge in March, entity B books it in April, and now you have a difference that isn't a difference. FX - both sides booked the same transaction at different rates, and the residual has to land somewhere sensible instead of in a plug. Coding - one side calls it a management fee, the other calls it a shared services recharge, and no automated matcher can see through that without help. And volume - hundreds of small transfers, none of them individually worth investigating, all of them collectively worth two days of someone's life.
None of those are hard problems intellectually. They're just tedious as hell, and they're distributed across people who don't report to each other, which is a governance problem dressed up as an accounting problem. That's why intercompany stays broken at companies that are otherwise excellent at the close.
What AI actually handles here
The matching layer is the obvious win and it's genuinely good now. Point a model at both sides of an intercompany pair and it'll match on amount, date proximity, reference strings, and counterparty naming variations, including the fuzzy cases where somebody typed the entity code wrong or the reference field got truncated. Rules engines have done exact matching for twenty years. What's new is that the messy 15% that used to fall out to a human now largely gets matched too, with a confidence score attached so you know what to look at.
The second win is explanation. Instead of a spreadsheet of unmatched items, you get an item with a proposed reason: this is a cut-off difference, entity B posts on the 3rd, here's the corresponding entry in the next period. That's the part that used to cost you an hour of email tennis with someone in another country and another timezone.
Third is the elimination entries themselves. For recurring, structurally identical eliminations - management fees, intercompany interest, standing recharges - drafting the entry is pattern work, and pattern work is what these tools are for. You review and post rather than build from scratch. If you want the same idea applied to the reporting layer, we walked through it in our piece on building the management reporting package with AI.
What it doesn't handle, and shouldn't
Transfer pricing judgment stays with you, permanently. Whether an intercompany charge is at arm's length is a tax and policy question with real consequences, and no model should be making that call unsupervised. Same with anything that changes the substance of a related-party disclosure, anything that touches an NCI calculation, and any elimination where the right answer depends on the group's legal structure rather than on the transaction.
And the honest caveat: a confident wrong match is worse than an unmatched item, because an unmatched item stays on your exception list where you'll see it, and a wrong match disappears. So set your auto-post threshold conservatively, keep a sample review even on the high-confidence bucket, and log everything the model did so your auditors can follow it. The audit trail requirement doesn't relax because a machine did the work.
The adoption number is the opportunity
APQC reports that 31% of organizations actively use AI in record-to-report, with another 39% still in early stages. Read that the way I do: roughly two thirds of finance functions have not operationalized this yet, which means the controller who gets intercompany matching running this quarter is early rather than late. It also means you're going to be doing it without a well-worn playbook from your peers, and honestly that's fine - the tooling is far more forgiving than it was even a year ago.
This is the same dynamic we wrote about in rolling reconciliations and the month-end close: the best practice has been sitting in the textbook for years, and what changed is that the grunt work underneath it finally got cheap. Intercompany is that story again, just with more entities and more people to chase.
Where I'd start
Take ONE entity pair. The two subsidiaries with the ugliest running difference, the ones that show up on your late list every single month. Pull both sides for the last three closes and let a model do the matching cold, then compare what it found against what your team found manually. You'll learn three things fast: how good the matching actually is on your data, which of your four failure modes dominates, and whether your reference data is clean enough to build on. That last one is usually the real blocker and it's better to find out on one pair than on forty.
Then fix the upstream thing the exercise exposes. Usually it's a coding convention nobody standardized, or a cut-off policy that two entities interpret differently, and fixing it is a one-page memo that saves you more days than the automation does. Then scale the matching to the next pair. That's the whole project - not a transformation program, just one ugly reconciliation at a time until the tail of your close stops being a negotiation.
If you're evaluating tools rather than building on top of your ERP, the consolidation and close category in our software directory is scored on features, support, value, and security, and it'll save you a few vendor demos.
Frequently asked questions
What is intercompany reconciliation?
Intercompany reconciliation is the process of agreeing transactions recorded between entities in the same corporate group, so that the amounts one entity records as receivable or income match what the counterparty entity recorded as payable or expense. Differences have to be resolved before those balances can be eliminated in consolidation.
Can AI do intercompany eliminations?
AI handles the preparation reliably - matching both sides of each pair, flagging timing and FX differences, proposing explanations, and drafting recurring elimination entries. The review, the transfer pricing judgment, and anything affecting disclosures or non-controlling interests still need an accountant to sign off.
How long should a monthly or annual close take?
APQC benchmarks put top-performing organizations at 10 days or less for the annual close, with a median of 18 days and slower performers at 35. Company size drives a lot of that spread: organizations under $100 million in revenue run a median of 10 days, while $1 billion to $5 billion companies run 23.
How many finance teams are actually using AI in the close?
APQC reports 31% of organizations actively using AI in record-to-report processes, with a further 39% in early stages of adoption. That leaves most finance functions with the opportunity still open.
What's the first intercompany process to automate?
Start with the entity pair that carries your largest recurring unexplained difference, and start with matching rather than posting. It's the highest-volume, lowest-judgment step, and it surfaces whatever data-quality problem is really driving your delays before you commit to a wider rollout.
Building this out and hiring for it? The close-heavy controllership and senior accounting roles are all over the Audit Friendly job board, refreshed nightly from 41,000+ companies.